· 15 min read
How do you fund an event before ticket revenue arrives?
Fund an event before ticket revenue arrives by reducing the amount due early, bringing confirmed receipts forward, and financing the remaining gap with money you can repay on a realistic sales forecast. Start with supplier payment dates, sponsor deposits and accessible ticket payouts. Then decide whether retained cash, owner funding or credit can cover what's left. If advertising is the specific obstacle, Loopyah's Kite can fund eligible events' ads, but it doesn't pay your venue or artist deposits.
The first thing you want to know is how much money you need and when. "We need funding for the event" is too broad to judge a loan, a sponsor offer or a payment extension. "We need $8,000 by next Friday, with repayment after final settlement" gives you something to compare.
Here's how to get to that decision without borrowing your way into an event that can't make money.
Check whether the event needs earlier cash or a different budget
A profitable event can run out of cash before doors open. A loss-making event can have cash in the bank because its owner has just funded it. Those situations need different answers.
Start with the event's expected revenue less all its costs, including ticketing deductions, sponsor delivery, refunds you expect to incur and financing charges. Test a slower-sales case as well. If the event loses money at a credible attendance level, change the costs, ticket offer or confirmed non-ticket revenue before adding debt. Our event break-even guide walks through that calculation.
Next, put the actual payment dates beside those numbers. A ticket sold today may reach your bank later. A signed sponsorship agreement may specify payment after the event. Neither receipt pays next week's invoice until the money is available.
Use an event cash-flow forecast to find the largest shortfall and the date it occurs. Keep a minimum operating reserve in the calculation. You still need room for a refund, a supplier change or a late receipt.
For every funding option, write down the amount available, its arrival date, all charges, what you promise in return, and when that promise falls due. Eliminate anything that arrives after the bill it needs to cover.
Ask suppliers to change the payment schedule
Look at your largest early invoices before looking for a lender. A smaller booking deposit or a balance payable after ticket settlement may reduce the amount you need to finance.
Make a specific proposal. Name the amount you can pay now, the next payment date and the receipt you expect to fund it. Ask what price or conditions would change. A supplier might agree, refuse, charge more or reduce the scope of the booking.
You need their agreement before changing a payment date. Quietly paying late puts the relationship and the event at risk. Australia's Business Queensland recommends negotiating agreed supplier terms and reviewing them to manage cash flow.
Check the full trade-off. A payment extension that adds a fee belongs in the budget. A smaller deposit that gives the venue a wider cancellation right may be expensive in a different way. Get the revised dates, amounts and booking conditions in writing.
Also check where the payment lands. Moving a production bill into the same week as a loan repayment may create a larger shortage later. Run the revised calendar through final settlement before accepting it.
This route is especially useful when the event is viable and a few early deposits cause the problem. It won't rescue a budget whose total costs exceed its realistic revenue.
Turn sponsor commitments into usable receipts
A sponsor can help fund the event early if the agreement requires payment early. The total package value alone tells you very little about its usefulness for cash flow.
Build the payment schedule into the proposal. You could ask for a payment on signing and a balance before the first major activation. Match that request to the work you will deliver and the costs you must commit. Don't promise extra benefits simply to get cash sooner without pricing their delivery.
The Australian government's payment terms guidance recommends putting payment timing and methods in both contracts and invoices. For an event, that means checking the sponsor's purchase-order process and invoice requirements before treating the due date as dependable.
Our event sponsorship proposal guide helps you define the package and its commercial value. For the funding decision, go one step further and calculate what the cash leaves available after sponsor-specific expenses.
Suppose a sponsor pays $5,000 early, but its activation requires $1,500 of new production spending before the same deadline. In this illustrative example, the deal contributes $3,500 towards other early bills. Counting the full $5,000 as spare cash would overstate its help.
Keep a prospective deal outside the committed funding plan until the agreement and payment requirements are settled. Even then, test a late-payment case. You may need a smaller backup facility or a supplier extension if the sponsor misses the date.
Use early ticket receipts without spending the refund reserve
Advance sales can fund delivery, but check the payout terms before building your plan around them. Find out when your own account receives funds, what deductions apply and whether any money will be held back. Use the confirmed payout arrangement for your event.
Work backwards from the bill. If the venue needs payment before your first payout can arrive, selling more tickets this week may improve the event's prospects without solving that immediate deadline.
Early-bird pricing can encourage purchases sooner, but discounts have a cost. An illustrative batch of 100 tickets sold for $40 instead of $50 gives up $1,000 of gross revenue if those same buyers would otherwise have paid full price. It also creates attendance and refund obligations. Don't describe that cash as free financing.
A limited release may still make sense when earlier sales provide useful demand evidence and help you meet commitments. Calculate the affordable quantity before opening it. Our early-bird ticket pricing guide shows how to check the effect on the whole event's revenue.
Separate gross sales from cash you can spend. Deduct payment and ticketing charges, applicable tax amounts and the refund reserve your circumstances require. Then account for any funded-ad recovery or other agreed deductions from the payout.
Presales work best when you already have an audience willing to buy and enough time for settlement. They are a fragile rescue plan when the event has weak demand and an invoice is due tomorrow.
Set a limit on owner funding
Retained business cash or an owner contribution may cover a modest shortfall without a new external lender. It still puts real money at risk.
Choose the maximum contribution before the next invoice creates pressure. Check what the business needs for payroll, taxes and other events. A healthy balance across the company does not mean every dollar is available for this show.
If you put personal money in, document whether it is a loan or an ownership contribution and agree how any repayment will work. Have your accountant check the treatment. Don't casually describe it as something you'll withdraw after the event if other obligations come first.
The same care applies to money from a friend, family member or co-promoter. Write down who can approve extra spending, who bears a loss and what happens if the event is postponed. A friendly agreement becomes harder to interpret once the money is gone.
Avoid topping up the same weak forecast repeatedly. If each sales update needs another owner transfer, revisit the event's size or viability before committing more.
Calculate the remaining funding requirement
Here's a worked example in USD. These are invented planning figures, not event-industry benchmarks or financing offers.
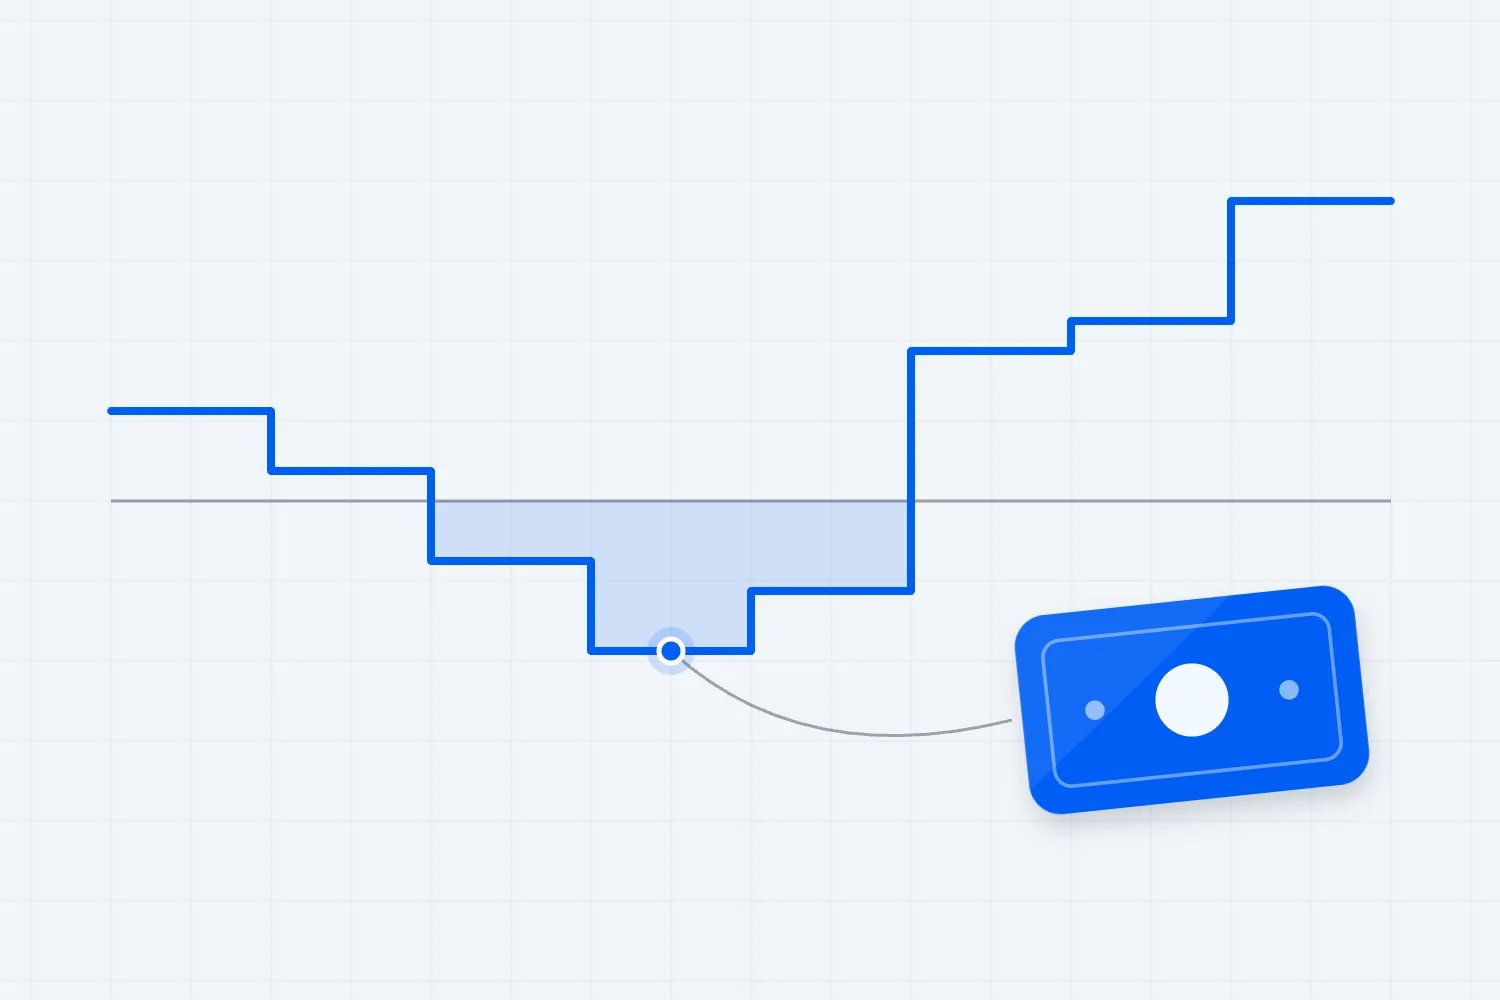
An organizer has $12,000 available and $30,000 of bills due before the first expected ticket payout. They also want a $2,000 minimum reserve. The initial funding requirement is therefore $20,000.
The organizer negotiates $4,000 of those bills into the week after the event. A sponsor agrees to move an existing $5,000 payment before the early deadline, with no extra delivery cost. The owner commits $3,000. Each change is documented and available in time.
The remaining funding requirement is $8,000.
| Label | Amount still needed |
|---|---|
| Initial need including reserve | 20000 |
| After supplier extension | 16000 |
| After earlier sponsor payment | 11000 |
| After owner contribution | 8000 |
This chart shows successive balances, so don't add its bars together. The calculation is $30,000 of early bills plus a $2,000 reserve, less $12,000 of available cash, then less $4,000, $5,000 and $3,000.
The event still owes the deferred supplier payment. The earlier sponsor receipt won't arrive a second time later. Owner money also has an agreed treatment. Update all those entries before deciding the remaining $8,000 is affordable to borrow.
Compare credit by repayment dates and total dollars
A line of credit can fit a temporary cash gap if you qualify and can repay it from realistic receipts. A term loan may have a different drawdown and repayment structure. Choose by the agreement in front of you, not the product's name.
Canada's Business Development Bank explains that lines of credit are designed for short-term cash needs and can be repayable on demand. That distinction matters when your expected repayment money depends on an event that hasn't happened. Confirm the terms that apply to your facility.
Ask each provider for the same information:
How much will actually reach the business after upfront deductions?
What interest, arrangement fees and other charges apply?
What payment is due on each date, including before the event?
Can the lender demand repayment or reduce the available facility?
What security or personal guarantee is required?
What changes if settlement is late, sales fall short or you repay early?
Put the answers into your forecast. A lower quoted charge can be a poor fit if payments start before your cash arrives. A larger facility can also tempt you to spend beyond the event's approved budget.
For the worked example, assume an invented offer provides the full $8,000 upfront and requires $8,400 after final ticket settlement. The $400 is the financing cost under this example's terms. It equals 5% of the borrowed amount, but that is not an annual percentage rate and should not be compared with annual interest rates as though it were one.
The principal repayment belongs in the cash-flow forecast. The financing charge belongs in the profit calculation. Subtracting the entire $8,400 as an event expense would count the borrowed principal as a cost when it isn't revenue in the first place.
Ask your accountant to review an unfamiliar offer, especially one with a guarantee, daily collections or charges that are difficult to translate into total dollars. Compare the amount and timing you receive with the amount and timing you must return.
Bring evidence to the funding conversation
A lender or funding partner needs to understand why the shortage exists. Give them an event-specific explanation supported by the business records they request. A polished audience forecast won't replace evidence of what has actually sold.
Prepare your signed venue and supplier commitments, the current event budget, bank balances, ticket sales and expected payout dates. Add confirmed sponsorship agreements and any existing debt payments that compete for the same cash. Keep unconfirmed opportunities visibly separate.
For a returning event, show the previous edition's actual result and sales pattern. Explain what has changed this time, such as capacity, ticket price or production cost. For a first edition, say so. Avoid presenting another event's sales curve as your own track record.
You should also be able to explain what happens if funding isn't approved. Could you reduce the production scope before signing, choose a smaller room or move a deposit deadline? Knowing that answer stops an urgent application from becoming a commitment to any terms offered.
Get the approval conditions in writing. Until the required documents are accepted and the money can arrive before your deadline, keep a pending application separate from available cash. That is the difference between a funding conversation and a funded event.
Use advertising funding for the advertising problem
Sometimes the production budget works, but you can't justify putting more cash into paid acquisition before knowing whether it will sell tickets. That is where Loopyah's Kite event advertising funding fits.
Kite funds and runs ads for eligible events using Loopyah's own Meta, Google and TikTok accounts. Your event first has to meet its own ticket-sales target. That unlocks ad funding, and subsequent campaign budgets depend on the sales the ads generate.
Under the terms described on the current product page, Loopyah recovers its ad spend plus a 5% fee on ticket sales attributed to those ads, from those sales. It does not take that recovery from tickets you sell yourself. Eligibility and the applicable terms still need checking for your event.
The practical benefit is specific. You can pursue eligible paid advertising without providing that campaign's upfront media spend. Kite does not provide cash for your artist guarantee, venue deposit or production invoice.
Keep the deductions in your event economics. Ticket revenue generated by ads is not all available to pay other suppliers, and you still have the costs of delivering the event to those buyers. Advertising funding does not make an otherwise unprofitable event profitable by definition.
If ads are part of your original cash gap, model Kite separately before borrowing for the same planned spend. Count only an approved arrangement, and don't turn a possible future campaign budget into money available in your bank account.
Treat grants and investment as separate routes
A grant may suit a cultural, tourism or community objective that genuinely matches the event. Check the program's applicant rules, eligible spending, application deadline and payment schedule. Ask whether it pays upfront or reimburses spending you must fund first.
Don't assume commercial events have access to general startup grants. In the United States, the Small Business Administration says it does not provide grants to start or expand a business. That doesn't rule out a specific local program. It means you need a named, eligible opportunity before putting grant money into the plan.
Investment has a different cost. The Australian government's funding guidance distinguishes borrowing from exchanging part ownership for capital. An investor may share risk, but they may also receive a continuing interest in the business and a say in decisions.
For a recurring event brand, that conversation may be worthwhile. For a short-lived payment gap, consider whether the lasting ownership consequences fit the problem. Agree how losses, extra funding and distributions work before accepting money.
If you consider public investment crowdfunding, get advice on the rules in your jurisdiction. A public offer of financial returns is a different undertaking from selling tickets to attendees. It needs its own preparation and shouldn't become an improvised deadline rescue.
Test repayment against a weaker sales result
Now return to the worked example. Assume the event expects $63,000 of receipts available after ticketing deductions and tax amounts set aside, including the sponsor payment. Its delivery costs total $60,000, including the $4,000 supplier bill moved later. Add the $400 financing charge.
The event leaves $2,600 before business-level overheads and tax on profit. That is the result after delivering the event and paying the financing cost. Borrowing doesn't add profit.
If receipts are $5,000 lower and delivery costs stay the same, the event loses $2,400. If receipts are $5,000 higher, it leaves $7,600. These deliberately simple scenarios hold costs constant so you can see the effect of sales risk.
| Label | Event result |
|---|---|
| 58000 receipts | -2400 |
| 63000 receipts | 2600 |
| 68000 receipts | 7600 |
Calculate repayment cash separately. In the expected case, $12,000 of opening cash plus the $3,000 owner contribution, $8,000 borrowing and $63,000 receipts, less $60,000 delivery costs and $8,400 repayment, leaves $17,600. That includes the capital brought into the event; it isn't all profit.
Check every earlier date too. A positive closing balance cannot pay an invoice that falls due before the receipts arrive. In the expected case, the illustrative calendar could work like this:
Before the early bills, opening cash, the sponsor receipt, owner money and borrowing provide $28,000. Paying $26,000 after the supplier extension leaves the $2,000 reserve.
Two weeks before the event, a $14,000 ticket payout arrives and $9,000 of costs are paid. Cash rises to $7,000.
In event week, another $22,000 arrives and $15,000 goes out. Cash reaches $14,000.
After the event, the final $22,000 arrives. Paying the remaining $6,000 of delivery costs, the deferred $4,000 and the $8,400 debt repayment leaves $17,600.
Those receipts and costs reconcile with the totals above. Now move $12,000 of the event-week payout into the final settlement. Event-week cash falls to $2,000, exactly the chosen reserve. Any additional delay would breach it even though the expected closing balance is unchanged.
Also ask what happens on cancellation. Identify buyer refund obligations, non-refundable deposits, sponsor commitments and any debt still due. Don't count on insurance or supplier credits unless the relevant terms support them. The owner should know how much further cash might be required before signing a guarantee.
If a reasonable delay breaks the repayment plan, renegotiate timing, arrange a confirmed backup or reduce commitments. Don't solve the spreadsheet by assuming the final release sells out.
Make the funding decision before the next commitment
The best event funding arrangement covers a specific cash shortage at a cost the event can carry. It arrives before the bill, leaves enough operating cash and has a repayment plan that survives more than the best-case sales forecast.
Start by changing payment timing where people agree, collecting confirmed sponsor money earlier and checking usable ticket payouts. Set a firm limit on owner exposure. Compare credit for the remaining gap, and use Kite where the need is eligible advertising spend.
Before you sign the next non-refundable commitment, write one sentence: "We need this amount on this date, these confirmed sources cover it, and these receipts pay it back." If you can't finish that sentence, the funding plan needs more work.

Author: By the Loopyah Content Team
The Loopyah Content Team shares expert insights, practical guides, and industry updates to help event organizers create unforgettable experiences and stay ahead in the event planning world.